

Best places to retire in Spain for expats
Best places to retire in Spain for expats in 2026 Spain has established…
If you’re a pensioner considering buying a property in Spain, there are mortgage options available, though requirements can be stricter for non-residents. Your eligibility for a mortgage will largely depend on your residency status and income sources, which can include state or private pensions, home equity, IRA contributions or other retirement plans.
Typically, mortgages for retirees may have shorter terms and higher monthly payments. However, Spain’s property prices are often lower compared to many other European countries, potentially giving you more equity if you sell your current property. Converting your funds into euros can also offer financial advantages.
As of July 2024, the average property price per square metre in Spain is €2,153, reflecting a 0.7% increase from the previous month and a consistent 2.7% rise since April 2024. The Spanish property market exhibits a notable imbalance between supply and demand, especially in urban centers and popular tourist destinations, which continues to drive up property values despite high inflation (3.5% in June 2024) and interest rates exceeding 3%. This imbalance is explored further in the article “What to Expect from the Spanish Property Market in 2026.”
Rental prices have been rising between 1% and 3% monthly since January 2024, though July experienced a 1.6% decrease. New government regulations limit annual rental increases to 3%, unless otherwise agreed upon or in the absence of a specific reference rate. This regulation is contributing to a shift from long-term to short-term rentals, resulting in a shortage of long-term rental options in major tourist areas.
When buying property in Spain, you’ll need a valid passport, an NIE number (Spanish Tax Identification Number for foreigners) and a Spanish bank account. The NIE is essential for purchasing property, allowing non-residents to acquire property in Spain.

A Spanish bank account is necessary for setting up direct debits for utilities and taxes post-purchase. It’s recommended to open this account before signing the purchase deed to ensure a smooth transition of utility and tax payments.
Key legal checks include:
For a full overview of the buying process, read our guide on how to buy property in Spain.
When purchasing property in Spain, it’s crucial to be aware of the various expenses beyond the asking price, including taxes that can significantly impact your investment.
Spanish banks typically finance 70% to 80% of the property’s value if it’s your primary residence, meaning you’ll need to save at least 20% to 30% for the deposit. Additionally, experts recommend setting aside an extra 10-12% of the property’s value to cover mandatory expenses and taxes, which can vary depending on the property’s price and location.
Purchase and Local Taxes: The taxes you’ll owe depend on whether the property is new or pre-owned. New builds are subject to a 10% VAT (IVA) and stamp duty (AJD), while pre-owned properties incur a property transfer tax (ITP), with rates varying by region. Additionally, you’ll be responsible for paying the annual property tax (IBI), which is based on the official value of the property.
Rental Income: If you rent out your property, the taxes you’ll owe will depend on your residency status. Residents may benefit from tax reductions, while non-residents pay a flat rate, with different rules applying to EU/EEA and non-EU/EEA residents.
Currency Exchange: Understanding currency risk is crucial, as fluctuations in exchange rates can significantly impact the cost of your investment. To protect against such risks, buyers can hedge by opening a foreign exchange (FX) position, which allows them to lock in favourable exchange rates. This strategy can help stabilise the cost of the property purchase, regardless of currency fluctuations, ensuring that unexpected costs are minimised.
Additional Costs: Beyond taxes, other costs include notary fees, land registry fees, property valuation and potentially a mortgage related cost.
Do you need a professional help for buy a house in Spain after retiring?
In 2024, the disparity in housing prices across Spain has grown significantly. According to Idealista, the highest price per square metre is €10,366 in the barrio de Salamanca in Madrid, while the lowest has dropped to €344 in Almadén, Ciudad Real. Affordable areas are found in six provinces: Córdoba, Ciudad Real, Toledo, Ourense, León and Murcia, whereas the priciest locations include San Sebastián, Barcelona, Madrid, Marbella, Palma de Mallorca and Bilbao.
Accurate property conveyancing is essential, as it ensures the property’s value is correctly assessed, helps prevent legal issues, and supports fair negotiations. Experienced solicitors in Malaga Spain provide independent legal advice and ensure a safe and secure transfer of property ownership.
The high demand in cities and popular coastal or tourist areas, combined with supply shortages and local regulations, has led to diverse real estate trends across Spain, with some areas stabilising and others experiencing rapid price increases. These trends are detailed in the article “What to Expect from the Spanish Property Market in 2024.”
Regional differences extend beyond property prices, as taxes on property purchases also vary significantly. For example, the general ITP tax on second hand properties is 10% in Catalonia and Valencia, but Canary Islands is 6.5% and the Balearic Islands are between 8% to 13%.
In 2024, the cost of buying a house in Spain varies depending on whether the property is new or a resale. Total expenses, including taxes and fees, typically range from 10% to 13% of the property’s purchase price.
Common Costs

Costs for New Properties
Costs for Resale Homes
Additional Considerations
Ongoing Costs (for new and resale homes):
For instance, the initial costs of purchasing a resale apartment in Malaga for €255,000 involves Property Transfer Tax (ITP) of 7%, totaling €17,850, notary fees of approximately €802,97 land registry fees around €383 and legal fees estimated at 1% of the purchase price plus VAT, which amounts to about €3,085.50. This is around 8% or/and 9% of the property’s value.
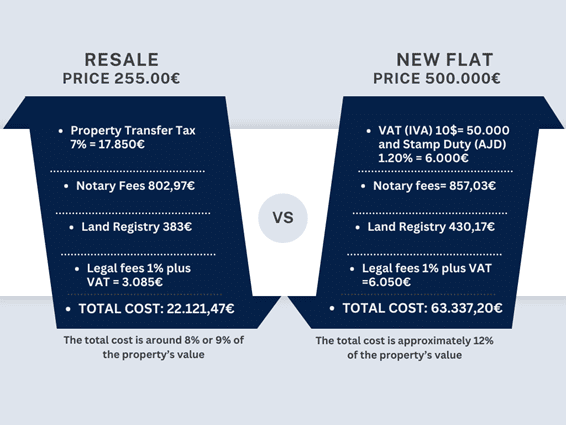
On the other hand, buying a new flat in Marbella for € 500,000 comes with different costs. You would incur VAT (IVA) at 10%, amounting to € 50,000 and Stamp Duty (AJD) at 1.20%, totaling € 6,000.00 Notary fees are roughly €857,03 land registry fees about €430,17 and legal fees estimated at 1% of the purchase price plus VAT, around €6,050. This is approximately 12% of the property’s value.
As shown in the previous comparison, purchasing a newly built home typically involves higher costs. At Tejada Solicitors, fees vary based on the complexity of the work and are not always charged as a fixed 1%
Obtaining a mortgage over the age of 50 is certainly possible, although it presents specific challenges. Banks often impose age limits on mortgage terms, typically requiring loans to be repaid by age 70 or 75, which can lead to higher monthly payments for older borrowers.
However, some financial institutions offer more flexible terms, extending repayment periods up to age 80, which can help alleviate financial strain. Additionally, pensions are generally recognized as a valid income source for mortgage applications, as long as they cover the mortgage payments without exceeding 35% of the total pension income.
Interest rates and loan durations vary for residents and non-residents in Spain. Residents usually benefit from lower interest rates and longer loan terms, while non-residents face higher interest rates and shorter loan durations. Mortgage requirements also differ: non-residents need a larger deposit, whereas residents usually require less. Demonstrating consistent income and a good credit score is essential for both groups, but non-residents must particularly show they manage their financial obligations effectively.
For details on the types of mortgages available in Spain for property purchases, refer to the article “Mortgage in Spain for Expats.” To secure better rates, it is advisable to apply early, ensure mortgage repayments do not exceed 35% of your salary, and consider using direct debit and additional bank products like insurance to potentially lower interest rates.
A property lawyer plays a key role in reviewing the property’s legal status, checking for any existing mortgage charges and overseeing the transaction process through a notary. They ensure that the public deed is properly drafted and that all tax obligations are met, including VAT for new properties and the Tax on Capital Transfers for used ones. After the sale, the lawyer handles property registration, safeguarding your ownership rights and providing guidance on addressing any defects or legal issues according to Spanish law. Their expertise provides peace of mind, ensuring the entire property purchase process is legally sound and secure.
The process of buying property in Spain as a foreigner begins with making a serious offer on your desired home. Once your offer is accepted, engage a lawyer to handle crucial legal checks before committing to a deposit or signing any documents. The purchase contract, which outlines the terms and conditions, including the deadline and any included fixtures or furniture, is then signed, with the buyer typically paying a 10% deposit.
If a mortgage is required, apply for it early, keeping in mind the approval timeline. Your lawyer will conduct essential checks, such as verifying property registration, ensuring proper planning permissions, assessing tax compliance and confirming community payments.
Following the contract signing, which usually occurs within two to eight weeks, the transaction is finalised at the Notary Public. Your lawyer will review the deeds, provide necessary translations and oversee the completion. Payment is made via a banker’s draft, and upon completion, you receive the keys to your new home. The lawyer also manages property registration, pays taxes and fees and sets up utility connections or transfers, including arranging direct debits.
For a more detailed walkthrough of each stage, read our complete guide on buying property in Spain as a foreigner.
Do you need a professional help for buy a house in Spain after retiring?

Finding a property in Spain on your own involves a mix of online and traditional methods. Online portals like Fotocasa and Idealista offer comprehensive searches, allowing you to set criteria like budget and location. These platforms provide a broad market overview, but beware of potential inaccuracies, unreliable contacts and outdated information. Traditional methods, such as driving around and looking for “se vende” signs, ensure direct contact with owners but are time-consuming and may not cover all available properties.
Alternatively, working with a real estate agent offers advantages like market knowledge and access to a portfolio of properties. However, agents may have limited options and typically represent the seller, which might not align with your best interests. When choosing an agent, prioritise those with strong local market knowledge, good communication and credentials like API registration.
Once you’ve found a potential property, conducting a property condition survey is essential. This survey assesses the urbanistic status, conservation state and structural integrity of the property, providing crucial information for informed decision-making.
The complex and extensive Spanish legislation on town planning can be challenging to navigate, especially for foreign buyers unfamiliar with local regulations. There may be hidden legal issues, such as unresolved property debts, zoning restrictions or planning permissions that could complicate the purchase process. Additionally, properties may have unresolved issues related to their structural condition or land classification that can lead to unexpected costs and delays. It’s crucial to thoroughly research and seek professional advice to avoid these common Legal mistakes foreigners make when buying property in Spain.
When you find a property in Spain that meets your needs, the next steps involve making an offer and signing a reservation agreement, known as a contrato de arras. This is a private agreement between the buyer and the seller that formalises a preliminary commitment to purchase the property. Also referred to as a deposit contract, it requires the buyer to make a payment as a sign of commitment, usually 10% of the value of the purchase. If either party fails to fulfil the agreement, a penalty may apply.
Key information included in the contract consists of the personal details of both parties, property details, the agreed sale price and payment method, the deposit amount and the deadline for signing the final sales contract.
This payment should be made into the lawyer’s client account, not directly to the seller.
The final step is signing the escritura pública (public deed), a formal process that transfers ownership from the seller to the buyer. This signing is arranged by the agents and lawyers during the arras (deposit) contract stage and takes place in front of a notary, a public official who ensures the legal validity of the transaction.
The notary confirms the payment of the purchase price and the handing over of the property keys. After this, your property lawyer will handle submitting the deed at the property register for public record, make sure the property’s taxes for the sale are paid and manage the transfer of the utilities to the new owner.
At Tejada Solicitors, we continue to offer our advice after the purchase of the property because as new owners, there are still annual tax obligations like IBI, Non-Resident Tax or tax on rental income. It is important to work with a Law Firm that can offer continuous support throughout your experience as a property owner or expatriate in Spain.
Do you need a professional help for buy a house in Spain after retiring?
Retiring in Spain offers both challenges and benefits. The pitfalls of retiring to Spain involve dealing with complex bureaucracy, financial planning and cultural adaptation. Adjusting to life away from family and friends can be tough, even with modern technology. Language barriers might make everyday tasks harder, although English is commonly spoken in some Mediterranean areas.
Success in retirement in Spain depends on careful planning and professional advice. This means understanding tax implications, managing finances wisely and selecting the right location and property. Working with experienced consultants and real estate agents can help ensure a smoother transition and a fulfilling retirement experience.
Despite these issues, Spain provides a high quality of life, thanks to its affordable healthcare, lower living costs and a wide range of property options.
Many retirees consult us about the tax implications and types of residence they can apply for if they choose to live in Spain as expatriates. Before making this important decision, we strongly recommend prior planning to avoid unexpected surprises. As expatriates, they will be taxed on their worldwide income in Spain. Additionally, pension plan withdrawals may be subject to taxation in Spain and any profit from the sale of their primary residence in their home country, if made while they are tax residents in Spain, will also be taxed in Spain. For more details, see our article on Exemption of capital gains tax on the sale of your primary residence abroad. In summary, expatriates in Spain would face the following tax obligations.
Article 9 (Personal Income Tax Law) states that individuals residing in Spanish territory for longer than 183 days or with primary financial interests in Spain must become tax residents in Spain. To fulfill this requirement, adherence to the following tax obligations is necessary:
Model 100 – Personal Income Tax (IRPF): Your global income, including capital gains, dividends, rental incomes, etc., will be subject to taxation in Spain. Establishing a double taxation agreement between Spain and your country of origin is essential to prevent double taxation.

Form 720 – Declaration of Assets: Completion of Form 720 is compulsory for individuals and legal entities to declare overseas assets that exceed €50,000 outside of Spain. This measure is crucial to avoid allegations of tax evasion.
Wealth Tax – This tax applies to worldwide net assets surpassing 3,700,000 euros.
Remaining informed and staying abreast of these obligations is paramount to fully embracing your residency in Spain.


“The only way to do great work is to love what you do.”
– Steve Jobs –
Contact Form
Best places to retire in Spain for expats

Non-Lucrative Visa Spain: Requirements and Application Process