


What is Form 151, and how to submit it?
What is Form 151, and how to submit it? Understanding the tax implications…
If you live in Spain and travel abroad for work, you may be eligible for one of the most valuable tax advantages in the Spanish Personal Income Tax system — the 7P exemption.
This incentive can exempt up to €60,100 per year from taxation under the IRPF for income earned from work carried out abroad, as long as specific requirements are met. In this article, we explain how it works, who can benefit from it, and what to keep in mind before including it in your tax return.
The 7P exemption is regulated by Article 7(p) of Law 35/2006 on Personal Income Tax (IRPF). It allows Spanish tax residents to exclude from taxation up to €60,100 annually of income earned from work effectively performed abroad.
In simple terms, even if you remain a tax resident in Spain, part of your income from foreign assignments may not be taxed in Spain. However, it will still be taken into account when calculating your overall tax rate (known as “income with progressivity”)
This exemption is established in Article 7(p) of the IRPF Law and Article 6 of its Regulation. The rule states that employment income derived from work carried out abroad is exempt, up to €60,100 per year, provided that the work benefits a non-resident company or a permanent establishment abroad.
Originally, this rule was designed to encourage the internationalisation of Spanish companies by facilitating the temporary relocation of their employees abroad. Today, it more broadly supports the international mobility of Spanish professionals who work outside the country while maintaining their Spanish tax residency.
One of the main elements of the 7P regime is the annual cap of €60,100.
To determine the exempt amount, your salary is prorated based on the number of days you actually worked abroad relative to the total number of days in the year. The interpretation of this calculation can vary slightly depending on the local tax office in charge of your case.
Secure your 7P tax benefits with expert guidance
The 7P exemption is not automatic for anyone who travels for work. It applies to certain professional profiles and specific circumstances.
In general, it’s aimed at Spanish tax residents who temporarily perform their duties abroad for a foreign entity. Typical examples include pilots, cabin crew, and seafarers working on international routes.
To qualify, you must maintain your Spanish tax residency certificate (under Article 9.3 of the IRPF Law). This means you must continue to meet the residency criteria (for example, spending more than 183 days in Spain during the year).
If you spend so much time abroad that you cease to be a tax resident, the 7P exemption will no longer apply, as you would then be taxed as a non-resident or under foreign tax laws.
The most common case involves employees of Spanish companies who are temporarily sent abroad to work on international projects.
The crucial condition is that the work must benefit a non-resident company or a foreign establishment, whether it’s a client or a subsidiary.
However, if your trip abroad serves an internal corporate purpose — such as training or product promotion — the exemption does not apply, even if you’re physically outside Spain.
Because the exemption only applies to employment income, self-employed workers generally cannot use it. Their income is considered professional activity, not employment. In such cases, alternative mechanisms, such as the double taxation deduction, may be more suitable.
For senior executives, Spanish courts have confirmed that they may be eligible for the 7P exemption if they can demonstrate that their work provided genuine value to the foreign entity. The Supreme Court ruling of 28 March 2019 recognised this right.
Work carried out in countries classed as non-cooperative jurisdictions (tax havens) is excluded, and the exemption cannot be applied if you lose Spanish tax residency during the relevant year.
H2: Requirements to apply the 7P exemption
To benefit from the 7P exemption as an IRPF taxpayer, several legal requirements must be met. Each of these conditions is reviewed carefully by the Spanish Tax Agency, so it’s essential to understand them clearly.
Tax residence in Spain: You must be a Spanish tax resident for IRPF purposes — generally meaning you spend more than 183 days a year in Spain or have your main economic interests located here.
Work effectively carried out abroad: The exemption applies only to work performed physically and effectively abroad, for a non-resident company or a foreign permanent establishment (Binding Ruling, 15-02-2019). The foreign entity or establishment must be the actual beneficiary of the work performed (Binding Ruling, 09-07-2019).
Foreign beneficiary entity: You must provide services to a non-resident company or a permanent establishment abroad that benefits directly from your work. This includes foreign subsidiaries or clients (Binding Ruling, 15-02-2019). Remote work from Spain is explicitly excluded (Binding Ruling, 04-06-2020).
Country with comparable taxation (not a tax haven): The country where you work must have a tax system similar to IRPF or a double tax treaty with Spain, and it must not appear on Spain’s list of non-cooperative jurisdictions (tax havens).
To apply the exemption correctly, you’ll need to calculate the number of days worked abroad, determine the portion of your salary that corresponds to those days, and gather proof of your assignment.
Be aware that the Supreme Court ruling of February 25, 2021, clarified that travel days to and from a foreign country also count as eligible days.
The Spanish Tax Agency usually considers all calendar days (including weekends and holidays) of your assignment abroad, as long as those days relate to the project. Days spent abroad for personal reasons before or after the work are excluded.
Protect your income abroad – consult our tax lawyers.
Once you have verified that the taxpayer complies with all the criteria set out in Article 6 of the IRPF Regulation and possess the necessary supporting documentation, the exemption must be properly reflected in your annual Spain income tax return (Model 100).
There is no specific form for the 7P exemption, and no prior authorisation is required, but it is essential to declare the exempt amounts correctly.
In Model 100 (IRPF), the portion of your income that qualifies under Article 7P should be entered in the section for “rendimientos exentos con progresividad” (“exempt income with progressivity”). This ensures that the amount is excluded from taxation but still taken into account for calculating your average tax rate — the rate applied to your remaining taxable income.
A frequent difficulty lies in accurately determining the number of days worked abroad and the corresponding portion of the annual salary.
An important reference is the Supreme Court ruling of 25 February 2021, which changed the previous interpretation in favour of taxpayers. Following this decision, both outbound and return travel days are now included in the calculation of eligible days.
According to the Tax Agency (Binding Ruling V2196-14), the calculation should include all calendar days of the foreign assignment — both working and non-working (weekends and public holidays). However, days spent abroad for personal reasons before or after the assignment cannot be counted.
It is essential to be ready to justify your claim for the 7P exemption before the Tax Agency. Always keep detailed records and documentation, including:
These documents will be your key evidence during a potential audit, proving that you spent a defined number of days abroad, worked for a non-resident entity, and that the country in question is not classified as a tax haven.
Several recurring errors can lead to the loss of the 7P exemption. The most common include:
The exemption does not apply to travel for commercial negotiations, market research, or work carried out in countries considered tax havens. It does apply, however, when a commercial trip is made for the benefit of a foreign subsidiary or non-resident entity (Binding Ruling, 13-03-2017). It does not apply if the taxpayer ceases to be a Spanish tax resident under Article 9 of the IRPF Law. Another frequent error is failing to apply the exemption correctly in payroll.
Check if you qualify for the 7P exemption in Spain.
Below are some common professional profiles and situations where the 7P exemption may apply:
The salary for that period could be exempt if all the requirements are met (working in Germany for a German subsidiary; the country is not considered fiscally advantageous).
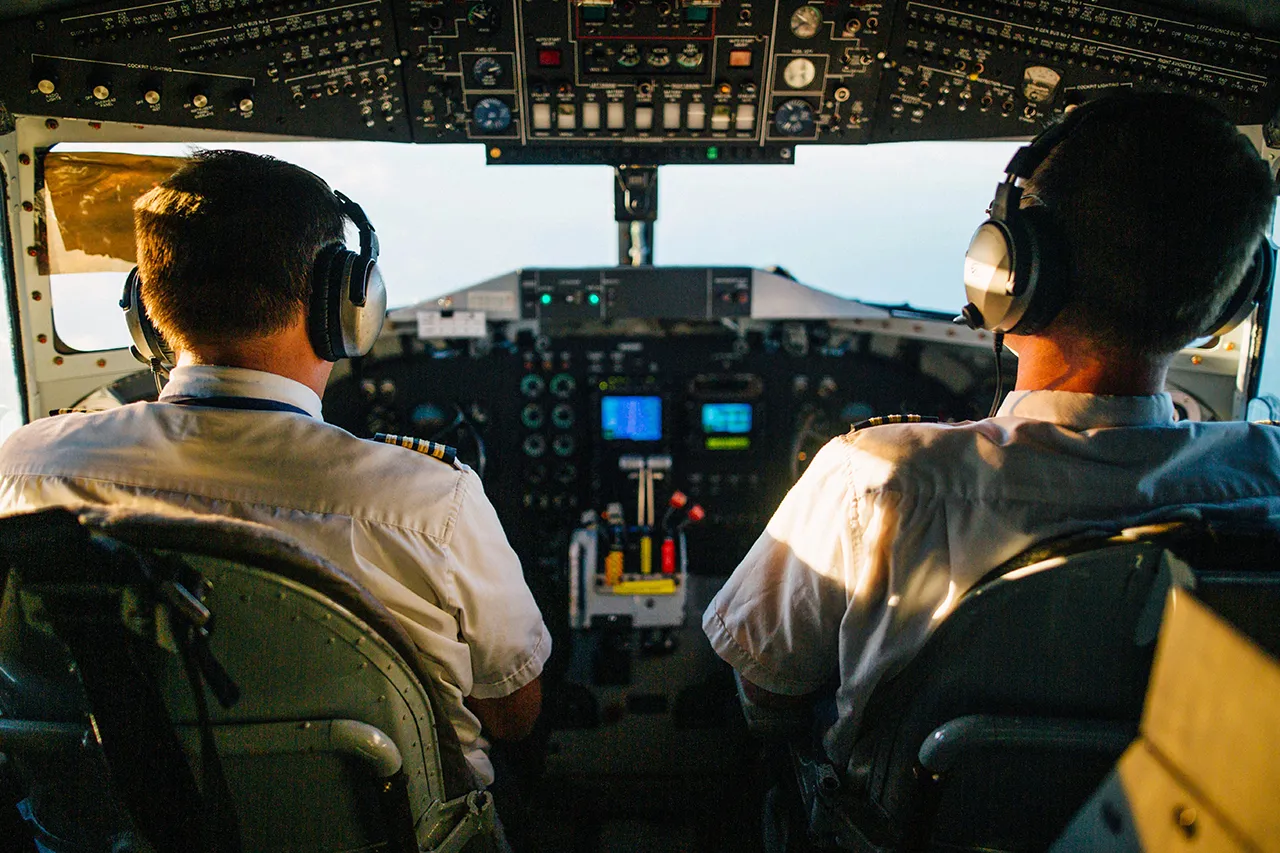
Pilots who are Spanish tax residents and employed by foreign airlines — for example, EasyJet Portugal or Ryanair based in another EU country — may benefit from the €60,100 IRPF exemption if they meet the legal requirements. For instance, a pilot residing in Málaga who works 140 days per year on international flights based in Lisbon may declare a proportional portion of their income as exempt.

Tax advisors specializing in international taxation assist expatriates in navigating the Spanish tax system. With over 20 years of experience, I provide tailored tax plans to optimize tax efficiency, ensuring compliance with regulations and minimizing dual taxation.
The Spanish Tax Agency is known for its strict scrutiny of this exemption. Almost every tax return that includes it is subject to verification.
Due to the complexity of the requirements, the evolving administrative interpretations, and the extensive case law surrounding Article 7P, Tejada Solicitors, led by Rosana Tejada, a specialist in these procedures, advises clients to carry out a complete review of their documentation before applying the exemption.
All evidence proving that the conditions are met should be carefully checked and organised. Even with proper preparation, interpretative discrepancies can still arise during a review or inspection.
If any requirement is not met, the Tax Agency will deny the exemption. There is no minimum number of days and no limit on the number of years you can benefit from the 7P exemption — it may be applied for every tax year in which the legal conditions are satisfied.
As previously mentioned, it is essential to document everything related to your work abroad — contracts or assignment letters, certificates from the foreign company, travel tickets and passport stamps, and payslips specifying the days worked abroad. The Tax Agency can review your return up to four years later, so maintaining proper records is crucial.
At Tejada Solicitors, we offer comprehensive tax advisory services for employees assigned abroad, combining our expertise in Spanish and international tax law. We can assist you in several specific ways to ensure you take full advantage of the 7P exemption.
We analyse your individual situation to confirm that you meet all 7P requirements and identify any potential issues. Our team helps you collect all necessary documentation — contracts, certificates, travel proofs, and more — before submitting your return. We highlight any weak areas and ensure your file is complete and well-supported.
We prepare your income tax return, applying the 7P exemption correctly, calculating the exempt income, entering it in the appropriate section, and verifying all figures. If the Tax Agency requests clarification or initiates a review, we represent you directly — submitting documentation, responding to queries, and defending your exemption. You can be confident that your case is in professional hands.
If you frequently work across different countries, Tejada Solicitors provides continuous international tax planning through a team of expert tax lawyers in Spain. Each year, we assess whether the 7P exemption or another regime (such as the Beckham Law for inbound taxpayers) is more advantageous. Our goal is to optimise your tax situation legally and efficiently, anticipate regulatory changes, and ensure you benefit from every available incentive without unnecessary risk.


No. The 7P exemption applies only to employment income. Self-employed workers cannot apply it to income from economic activities; instead, they must use other mechanisms, such as the international double taxation deduction or alternative tax planning.
The “expatriate” regime is compatible with the per diem (dietas) scheme (Binding Ruling V0333-10) provided the foreign assignment lasts less than nine months. However, it is not compatible with the “excess regime.” The taxpayer may choose to apply one or the other

“The only way to do great work is to love what you do.”
– Steve Jobs –
Contact Form
